Residential appraisal
Residential appraisal for hail, wind, water and fire losses
Most residential appraisals on the Front Range turn on a few recurring questions: whether a roof can be repaired or has to be replaced, which items were left out of the estimate, and whether the pricing reflects current local costs. We settle those by inspecting and measuring the property, documenting the damage, and comparing a complete estimate with the other side's, line by line.
Types of loss
Hail
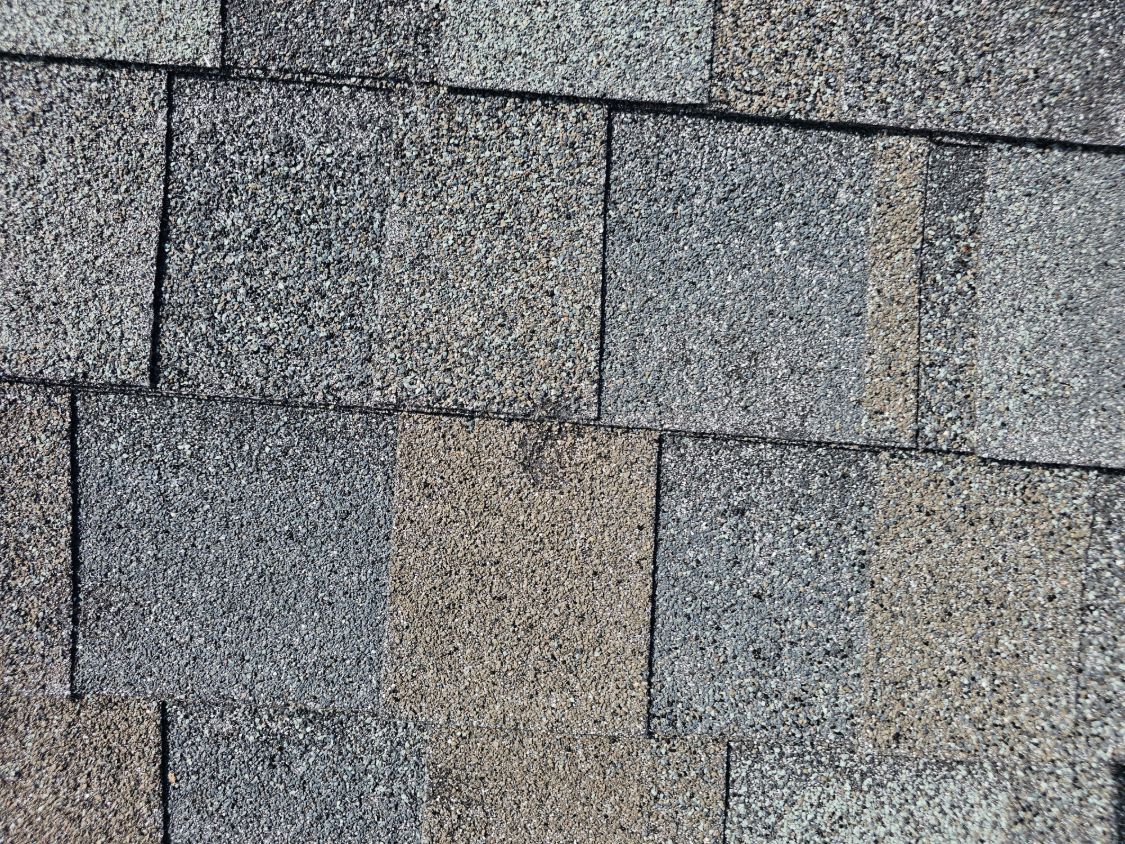
Asphalt, metal, tile and wood roofs. Test squares and slope-by-slope documentation, soft metals, siding, screens, decks and painted surfaces. Matching and line-of-sight questions on partial approvals.
Wind
Creased and lifted shingles, missing sections, fence and outbuilding damage, and the question of whether a roof that has been lifted can be resealed or needs replacement.
Water and freeze
Burst pipes, ice dams and appliance failures, with the resulting drywall, flooring, cabinetry and contents damage.
Fire and smoke
Structural repair, smoke cleaning versus replacement, and contents where the policy brings them within the appraisal.
What the engagement includes
- An inspection of the property, arranged jointly with the carrier's appraiser whenever possible.
- Roof measurements, test squares and a photographic record by slope and elevation.
- A complete line-item estimate using current regional pricing, with depreciation applied as the policy provides.
- A side-by-side comparison with the carrier's estimate and a meeting with the carrier's appraiser to resolve the differences.
- If an umpire is needed, early agreement on the umpire and a clear presentation of the disputed items.
- A signed award stating replacement cost and actual cash value, with the photo report and estimate for your records.
If you already have a contractor: appraisal does not change who performs the repairs. It determines the amount. Your contractor remains your contractor, and the award gives both of you a settled figure to work from.
Typical timeline
First few days
We review both estimates, confirm that appraisal applies, and provide the wording for the appraisal demand.
Weeks one to four
The carrier names its appraiser, most policies allow 20 days, and the appraisers agree on an umpire.
Weeks three to six
Joint inspection, estimate prepared, comparison exchanged, appraisers meet.
Weeks five to twelve
Award signed by the two appraisers, or by one appraiser and the umpire. The carrier issues payment under the policy.
Request a residential appraisal
Send both estimates to Appraisals@HeidmannAndAssociates.com and we will reply within one business day.